Understanding Liability and Insurance for Estate Sales in California
Explore liability concerns and insurance coverage related to estate sales in California, including legal considerations and professional services.
- Legal Considerations for Estate Sales in California
- Handling Disputes and Liabilities
- Liability concerns and insurance coverage for estate sales
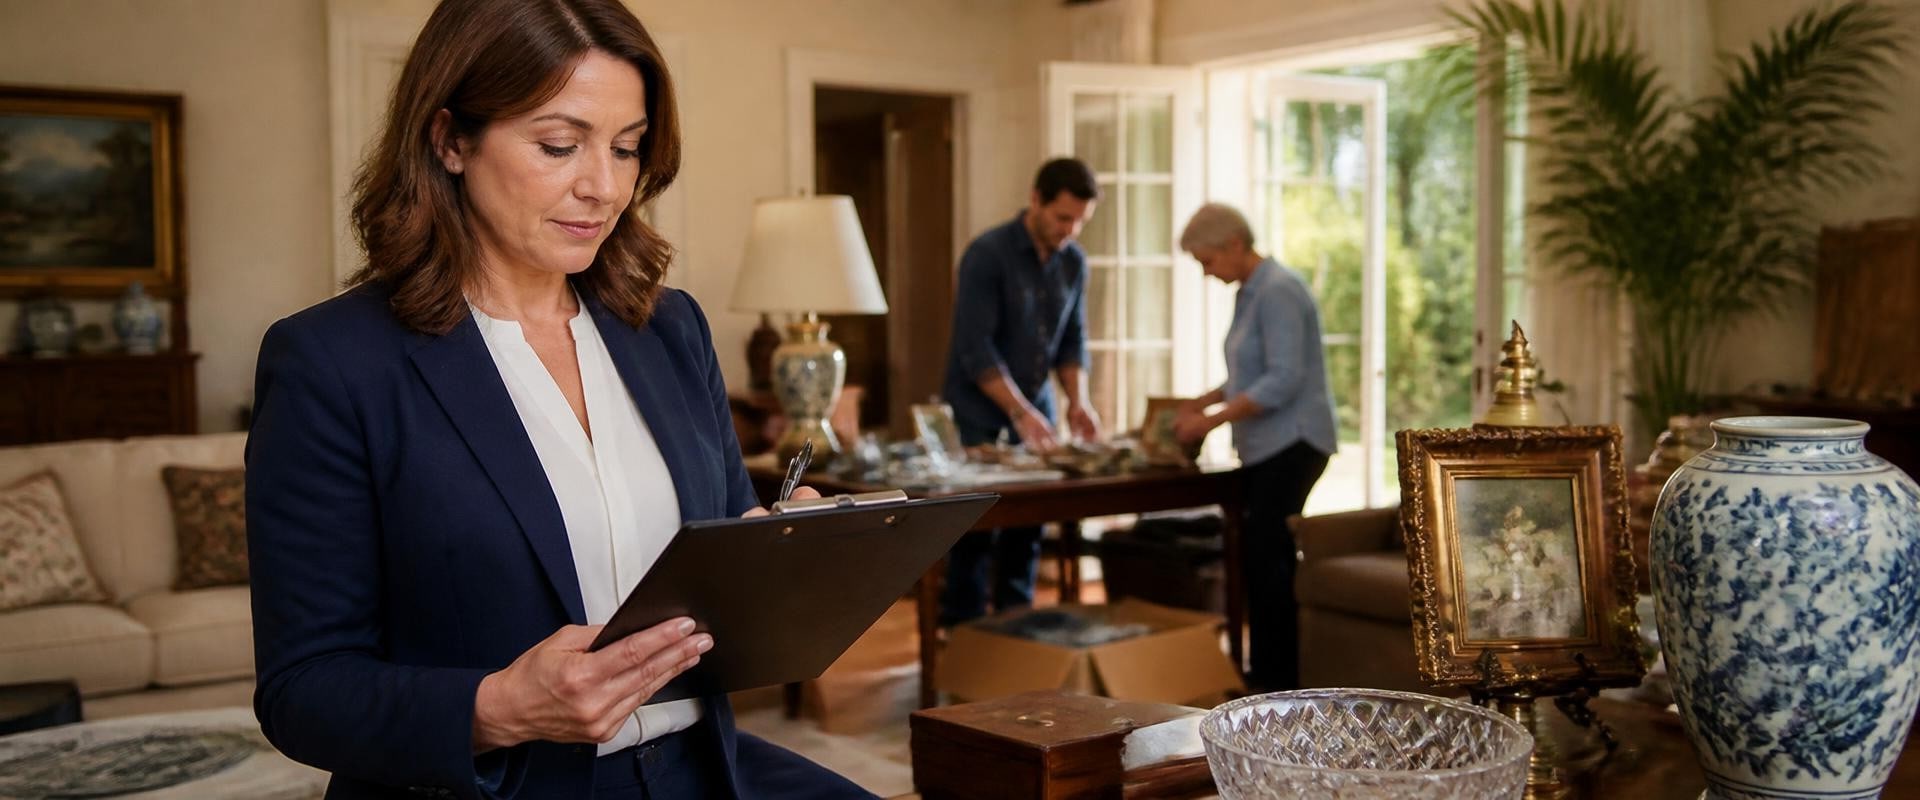
When it comes to estate sales, many people often overlook the critical aspects of liability concerns and insurance coverageliability concerns and insurance coverage. These factors are not merely secondary considerations; they are essential components that can protect both sellers and buyers during the sales process. In California, where estate sales can attract a wide array of potential buyers, understanding the legal implications of hosting such an event becomes paramount. Estate sales typically involve selling off personal belongings from a deceased person's estate or liquidating assets from a downsizing situation. While they can be an effective way to generate revenue and clear out space, they also come with their share of risks.
From accidental injuries occurring on the premises to potential disputes over the authenticity or condition of items sold, the pitfalls are numerous. Hence, having a robust understanding of liability concerns is vital for anyone considering organizing an estate sale. Moreover, navigating the world of insurance coverage for these events can be daunting. Many individuals are unaware that standard homeowner's insurance policies may not fully cover incidents that occur during an estate sale. This lack of awareness can lead to significant financial repercussions if something goes wrong.
Therefore, it is crucial to explore the various types of insurance options available specifically for estate sales in California. This article aims to shed light on these important topics, providing insights into how to adequately prepare for an estate sale while safeguarding yourself from potential liabilities. Whether you are a seller preparing for your first estate sale or a buyer looking to understand the risks involved, our comprehensive guide will equip you with the knowledge needed to navigate this complex landscape effectively. Estate sales have seen a surge in popularity in California, particularly during periods of estate liquidation. This growing trend comes with its own set of challenges, especially concerning Therefore, it is crucial to explore the various types of insurance options available specifically for estate sales in California. This article aims to shed light on these important topics, providing insights into how to adequately prepare for an estate sale while safeguarding yourself from potential liabilities. Whether you are a seller preparing for your first estate sale or a buyer looking to understand the risks involved, our comprehensive guide will equip you with the knowledge needed to navigate this complex landscape effectively. Estate sales have seen a surge in popularity in California, particularly during periods of estate liquidation. This growing trend comes with its own set of challenges, especially concerning liability concerns and the necessary insurance coverage to protect all parties involved. Understanding these aspects is crucial for individuals organizing estate sales or seeking professional help, as it ensures that both sellers and buyers are safeguarded during these transactions. One of the primary liability concerns associated with estate sales is the potential for injuries occurring at the sale site.
Given that these events often attract large crowds, the likelihood of accidents increases significantly. For instance, a customer might slip and fall due to wet floors or uneven surfaces, leading to severe injuries and potentially hefty medical bills. In such cases, the property owner or the individual conducting the sale could be held liable for not maintaining a safe environment. Another common issue arises from disputes over item ownership. Inherited items can sometimes lead to conflicts among family members or other interested parties, especially if there are disagreements regarding who has the right to sell certain items.
These disputes can escalate quickly and may involve legal action, which can further complicate the estate sale process and lead to additional liabilities. The role of professional estate sale companies becomes vital in mitigating these risks. These companies often have experience in handling the complexities of estate sales and are usually equipped with strategies to minimize liability issues. They typically have protocols in place to ensure that the sale environment is safe and compliant with local regulations. Furthermore, professional estate sale organizers usually carry their own insurance coverage, which can provide an extra layer of protection for all parties involved. In California, there are various types of insurance coverage available for estate sales.
One of the most crucial types is general liability insurance, which protects against claims of bodily injury or property damage that might occur during the sale. For example, if a customer were to trip over a display table and sustain an injury, general liability insurance would cover medical expenses and legal fees incurred due to the incident. Another important type of coverage is property insurance, which protects items being sold from potential damage or theft during the sale. This is particularly relevant in cases where valuable antiques or collectibles are being sold; having this insurance can provide peace of mind for both sellers and buyers alike. To illustrate how liability concerns can manifest in real scenarios, consider a situation where a customer argues over the appraisal value of an item. If the item was improperly valued, it could lead to accusations of fraud or misrepresentation, resulting in legal disputes that may require resolution through mediation or even court proceedings.
Such scenarios underscore the importance of accurate appraisals and transparency during estate sales. Moreover, understanding local laws can significantly impact liability issues. Different municipalities may have specific regulations governing estate sales, including permits required for public gatherings or safety standards that must be adhered to. Being aware of these laws can help mitigate risks and ensure compliance, thereby reducing potential liabilities. Some readers may argue that estate sales do not carry significant risks, believing that they are simply casual events with little at stake. However, this perspective often overlooks the complexities involved in such transactions.
The reality is that without proper knowledge of liability concerns and adequate insurance coverage, both sellers and buyers can find themselves facing unexpected challenges that could lead to financial loss or legal trouble. In conclusion, as estate sales continue to grow in popularity across California, it becomes increasingly important for organizers and participants to recognize and address liability concerns. By understanding the various risks associated with these events and ensuring appropriate insurance coverage, individuals can protect themselves effectively during estate liquidation processes.
Legal Considerations Specific to California
When organizing an estate sale in California, it is crucial to be aware of the local laws and regulations that govern these transactions. Each municipality may have its own set of rules regarding estate sales, which can include necessary permits and specific seller disclosures. First and foremost, many cities require a permit to hold an estate sale. This permit may need to be obtained from the local city or county office, and it often involves filling out a simple application form.Some areas also impose restrictions on the days and times when estate sales can occur, so it’s essential to check with local authorities before planning your sale. Additionally, sellers are typically required to provide certain disclosures to potential buyers. This includes details about any known defects or issues with items being sold, as well as any relevant information about the property where the estate sale is taking place. Transparency in these disclosures helps protect sellers from future liability claims by buyers who may feel misled after the sale. Understanding these legal considerations not only safeguards the seller but also ensures a smooth transaction for all parties involved. It is advisable for individuals organizing estate sales or seeking assistance from professional estate sale companies to familiarize themselves with these regulations to avoid potential legal pitfalls.
Finding Professional Services for Estate Liquidation
When organizing an estate sale, it is crucial to find reliable estate sale companies that can assist with both the logistics of the sale and the legal and insurance matters involved.Here are some tips to help you identify trustworthy professionals. Firstly, consider seeking recommendations from friends, family, or colleagues who have previously organized estate sales. Personal referrals can provide valuable insights into the quality of service offered by different companies. Secondly, conduct thorough online research. Look for estate sale companies with strong online presence, including a professional website and active social media profiles. Read customer reviews and testimonials to gauge their reputation and track record. It is also important to check for any necessary licenses and certifications that demonstrate the company’s compliance with state regulations.
A reputable estate sale company should be able to provide proof of their insurance coverage, which protects both you and the buyers during the sale. Additionally, schedule consultations with potential companies to discuss your specific needs and ask about their experience with legal and insurance matters. A professional company should be knowledgeable about liability concerns and willing to guide you through the complexities of insurance coverage for estate sales. Finally, compare fees and services offered by different companies. Ensure that you understand what is included in their pricing, such as advertising, staffing, and any additional legal support they may provide. This will help you make an informed decision when selecting a professional service for your estate liquidation.
Understanding Insurance Coverage Options
When organizing an estate sale in California, understanding insurance coverage options is vital for protecting both sellers and buyers from potential liabilities.There are several types of insurance policies that can be beneficial in this context, ensuring that all parties involved are safeguarded against unforeseen events. One of the primary types of insurance relevant to estate sales is general liability insurance. This policy can protect the seller from claims arising from injuries or accidents that occur during the sale. For instance, if a customer trips and falls on the property, general liability insurance can cover medical expenses and legal fees associated with the incident. Another important consideration is property insurance. This type of insurance covers any damages to items being sold during the estate sale.
If valuable items are damaged or lost due to unforeseen circumstances, such as a natural disaster or theft, property insurance can help mitigate financial losses.
Event insurance
is also worth exploring for those conducting estate sales. This specialized policy can cover a range of liabilities associated with hosting an event, including any potential damages to the venue or issues arising from crowd control. It provides an extra layer of protection, especially for larger estate sales that may attract many attendees. Lastly, sellers should consider whether they need professional liability insurance, particularly if they are hiring an estate sale company to manage the sale on their behalf. This policy can protect against claims related to negligence or failure to perform professional duties. In summary, understanding the various insurance coverage options available for estate sales is crucial for protecting against potential liabilities.By securing the right types of insurance, sellers can ensure a smoother transaction and provide peace of mind for both themselves and the buyers involved in the sale.
Tips for Organizing a Successful Estate Sale
Organizing a successful estate sale requires careful planning and attention to detail, especially when it comes to liability concerns and ensuring adequate insurance coverage. Here are some practical tips to help you navigate this process effectively.1.Pricing Items Appropriately:
Start by researching similar items to determine fair market prices. Consider hosting a preview day where potential buyers can view items before the sale. This not only generates interest but also allows you to gauge pricing expectations.Remember, overpricing can deter buyers, while underpricing may lead to financial losses.
2.Marketing the Sale:
Utilize various marketing channels to promote your estate sale. Leverage social media platforms, community boards, and local classifieds to reach a wider audience. High-quality photos and detailed descriptions of items can attract more potential buyers. Clearly state the sale date, time, and address in all your promotions.3.Ensuring a Smooth Sale Process:
To facilitate a seamless transaction, create an organized layout for your sale.Group similar items together and provide clear signage. Having enough staff on hand to assist buyers can enhance their experience and minimize confusion. Consider implementing a ticketing system for high-demand items to manage buyer flow efficiently.
4.Addressing Liability Issues:
Make sure you understand liability concerns associated with estate sales. Consult with an insurance professional to ensure you have sufficient coverage in place.This may include general liability insurance to protect against potential accidents or injuries occurring during the sale.
5.Providing Clear Terms of Sale:
Establish clear terms regarding payment methods, returns, and item conditions. Display these terms prominently at the sale to avoid misunderstandings. Inform buyers that all sales are final unless otherwise stated, which can help mitigate disputes later on. By following these tips, you can organize an estate sale that not only maximizes profits but also protects all parties involved from potential liabilities.Common Liability Issues in Estate Sales
Estate sales have gained significant traction in California, serving as an effective means for individuals to liquidate assets during estate proceedings. However, with the growing popularity of these events comes a range of liability concerns that must be addressed to protect both sellers and buyers.Understanding these potential issues is vital for anyone involved in organizing or participating in estate sales. One of the primary liability issues arises from accidents on the property. During an estate sale, numerous individuals may traverse the premises, increasing the likelihood of slips, trips, and falls. For instance, if a buyer trips over an uneven surface or a cluttered area while inspecting items for sale, the property owner could be held liable for any resulting injuries. It’s crucial for sellers to assess their property for hazards and take necessary precautions to mitigate these risks. Another common scenario involves disputes over item ownership.
Estate sales often feature personal belongings that may have complex ownership histories. If a buyer purchases an item believing it to be for sale, only to discover that another family member claims ownership, legal disputes can arise. This not only complicates the transaction but can also result in liability for the seller if proper documentation or clarity regarding item ownership is not established prior to the sale. Additionally, misrepresentation of items can lead to liability issues. Sellers must accurately represent the condition and value of items being sold.
If a buyer discovers that an item was misrepresented—such as a piece of art being sold as an original when it is actually a reproduction—they may pursue legal action against the seller for fraud or breach of contract. In summary, understanding these common liability issues—ranging from accidents on the property to disputes over item ownership—is essential for anyone organizing or participating in an estate sale. By taking proactive measures to address these concerns, sellers can better protect themselves and ensure a smoother transaction process. In conclusion, navigating the liability concerns and insurance coverage associated with estate sales in California is essential for both sellers and buyers. As discussed, understanding common liability issues can help mitigate risks during these transactions, while being aware of insurance coverage options provides a safety net against unforeseen events. Additionally, the legal considerations specific to California must be taken into account to ensure compliance and protection. Engaging professional services for estate liquidation can streamline the process and reduce potential liabilities.
Lastly, thorough planning and organization are key to a successful estate sale, allowing participants to focus on the value of the items being sold rather than the legal implications. By being informed and prepared, individuals can avoid potential pitfalls and ensure a smoother experience for everyone involved in the estate sale.
Gerardo Liverani
Gerardo Liverani is a seasoned expert in California estate sales and estate liquidation, bringing years of experience to help individuals navigate the complexities of selling inherited items and organizing successful estate sales. With a deep understanding of the legal considerations and best practices specific to California, Gerardo provides actionable insights and strategies for pricing, marketing, and conducting estate sales effectively. Whether you're looking to hire a professional estate sale company or want to tackle the process yourself, Gerardo's expertise ensures that you are well-equipped to make informed decisions throughout your estate sale journey.